01
Free Assessment
Share your loan details. We analyze your debts, calculate possible reduction, and explain the process.
Whether it's a personal loan, credit card, business loan, or multiple debts together — we negotiate with lenders to reduce your outstanding amount and stop harassment permanently.
Each service is designed for a specific type of debt. Click on any service to learn exactly how we help.
Negotiate reduced payoff for personal loans from banks and NBFCs.
View Details →Reduce outstanding credit card dues and stop accumulating interest.
View Details →Consolidate and settle multiple loans together with one plan.
View Details →Settle business loans while protecting your enterprise operations.
View Details →
Personal loans from banks or NBFCs can become unmanageable due to job loss, medical emergencies, or income reduction. We negotiate with your lender to reduce the total payable amount — often by 40-60% of the outstanding balance.
Review your loan details — principal, interest, penalties, and lender communication
Send legal notice to bank/NBFC citing RBI guidelines and your financial hardship
Negotiate reduced one-time settlement — typically 40-60% of outstanding amount
Stop all harassment, get settlement letter, and close the loan account
Credit card debt grows fast — 36-40% annual interest means your balance doubles in roughly 2 years if you only pay minimum dues. We negotiate with banks to close your card with a one-time reduced payment, stopping the interest spiral permanently.
Analyze your card statement — total dues, interest charged, late fees, and GST components
Send legal notice to card issuer requesting settlement and stopping harassment
Negotiate one-time settlement — typically 50-70% off total outstanding
Get No Due Certificate / settlement letter and close the card permanently
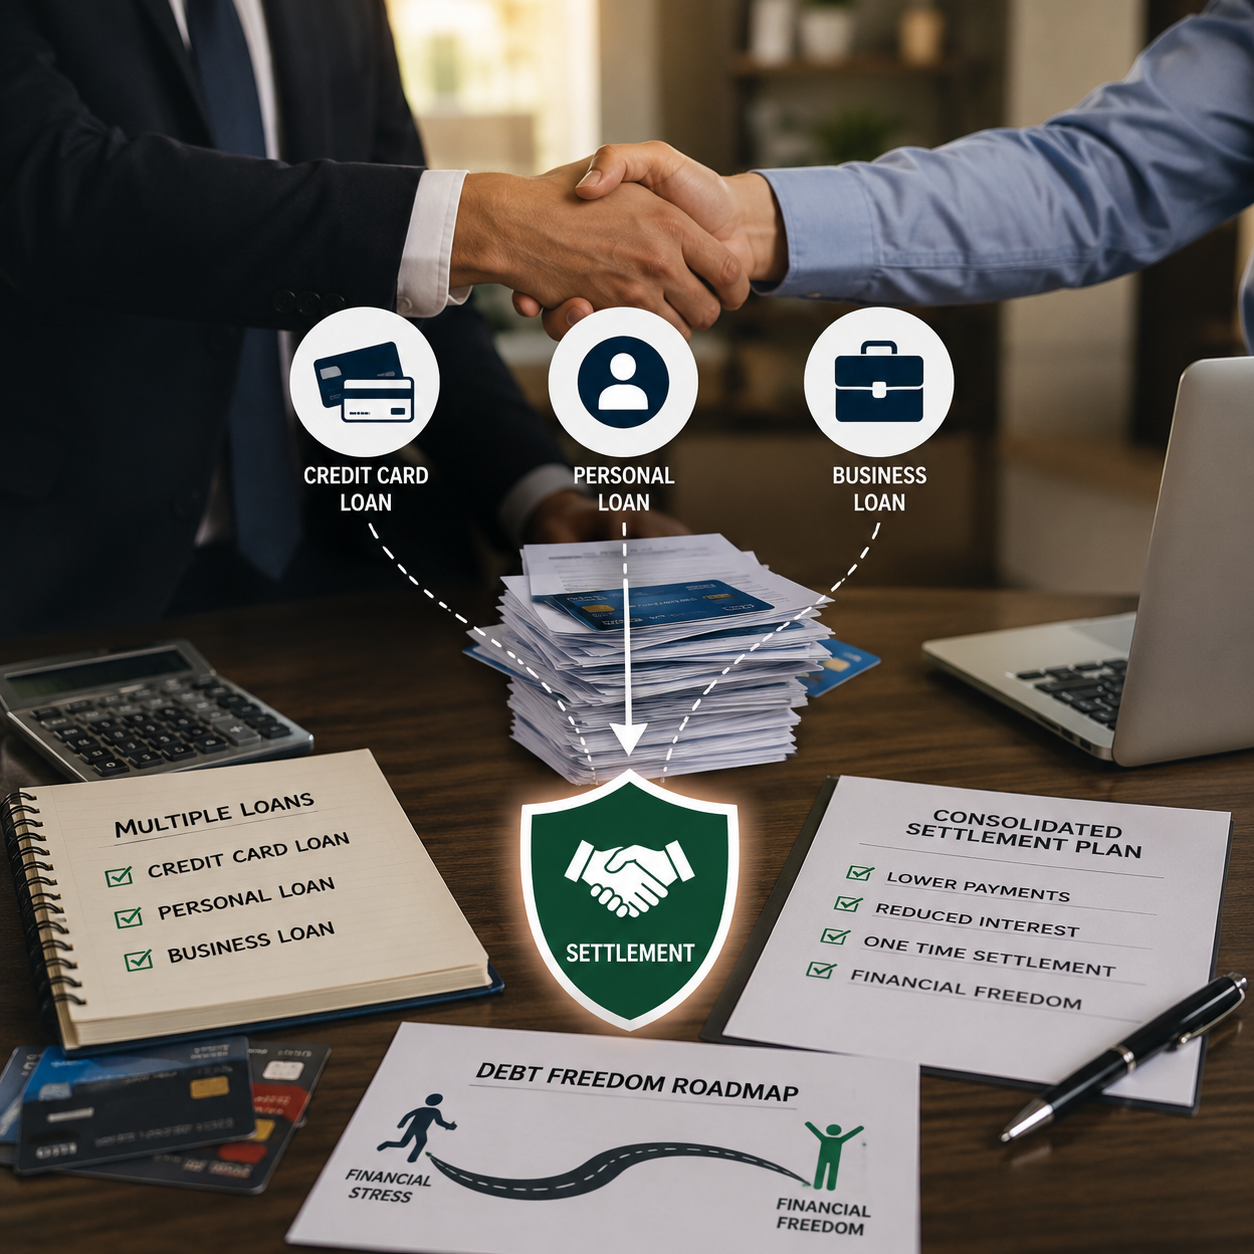
When you have 3, 5, or even 8 different loans — personal loans, credit cards, car loans — paying even minimum EMIs becomes impossible. We create a single consolidated plan and negotiate with each lender simultaneously to settle everything together.
Complete debt audit — list all loans, outstanding amounts, interest rates, and statuses
Priority ranking — which loans to settle first for maximum relief
Parallel negotiation with all lenders — legal notices sent to each simultaneously
Systematic closure — settle each loan one by one, get No Due Certificates for all
Business loans are often secured — meaning lenders can threaten to seize your business assets, inventory, or property. We protect your business while negotiating a reduced settlement that allows you to continue operations without the burden of unmanageable debt.
Assess loan type — secured, unsecured, overdraft, cash credit — and collateral status
Legal response to SARFAESI/DRT notices — protect your assets from auction
Negotiate with bank for reduced settlement — protect business continuity
Get settlement done, unfreeze accounts, and get your business back on track
A clear 4-step process that takes you from first call to loan closure.
Share your loan details. We analyze your debts, calculate possible reduction, and explain the process.
We send a formal legal notice to your lender citing RBI guidelines, your hardship, and settlement request.
Our team negotiates with the bank's settlement cell for maximum reduction on your total outstanding.
Pay the agreed amount, receive No Due Certificate, and your loan is permanently closed.
Many people try to negotiate directly with banks. Here's why that rarely works.
Reduction depends on your loan type, outstanding amount, lender, and your financial situation. Personal loans typically see 40-60%, credit cards 50-70%, and business loans 30-55%. We assess your case during the free consultation and give you a realistic estimate.
Settlement does impact your CIBIL score — it shows as "settled" rather than "closed." However, continued non-payment and harassment damages your score and mental health far more. Many clients rebuild their score within 1-2 years after settlement.
Secured loans like home loans are more complex because collateral is involved. We can help protect your asset and negotiate, but the approach differs from unsecured loans. Contact us for a case-specific assessment.
If the bank initially rejects, we escalate through RBI Ombudsman complaint, consumer court filing, or other legal channels. Most cases settle during or after this escalation. Rejection is not the end — it's often the beginning of serious negotiation.
In most cases, banks require a one-time lump sum payment for settlement. However, in some situations, we can negotiate a 2-3 installment plan. This depends on the lender and your specific case.
Free, confidential assessment. No obligation. Just honest advice about what's possible for your situation.